Practical guide
Credit control before shipment: designing the decision flow
Credit control before shipment checks an order against the customer’s credit limit, overdue receivables and recorded payments before goods leave the warehouse. The decision should release the order, block it or send a controlled exception for approval.
- Pre-shipment Receivables Control
- Finance & AR for Distribution Credit Control
- Aktashwater: accounts receivable broken down by product group
In detail
An accounts receivable report describes a position that already exists. Operational control starts earlier, while a new order can still be held, its terms changed or an exception sent to the accountable approver.
The decision needs one consistent view of the order value, available credit, open documents, ageing and recorded payments. When those inputs refresh on different schedules, a block can appear arbitrary to sales and warehouse teams.
An exception should not erase the rule. It records who authorised the shipment, why the decision was made and which order it covered, so the finance team can review the outcome in context.
How it is applied
- The order enters the check with the customer, payment terms and value of the new exposure.
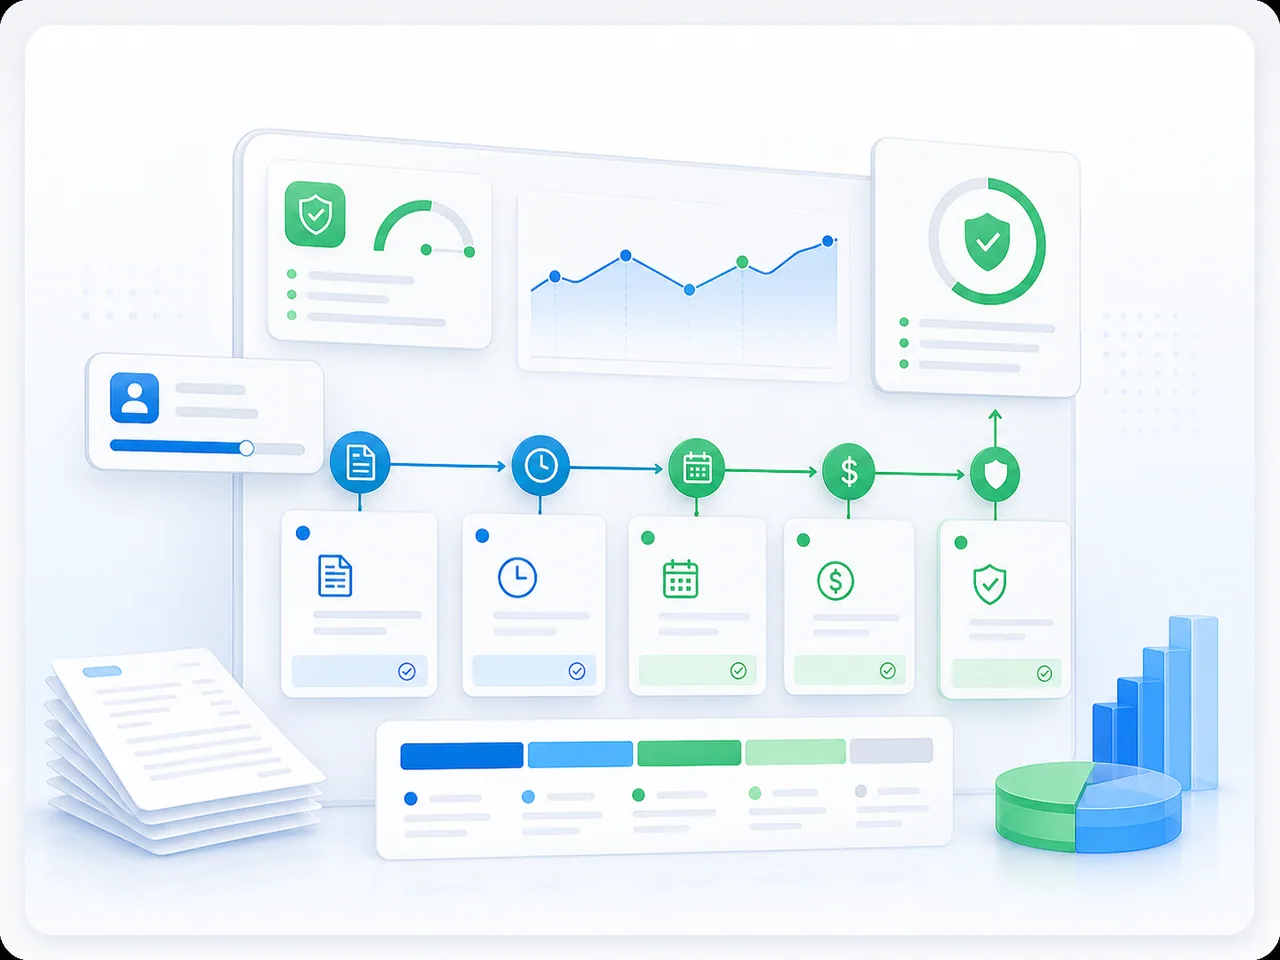
- The process collects available credit, open receivables, ageing and recorded payments from the agreed sources.
- The rule returns a release, a block or a request for an exception approval.
- The accountable approver records the decision and reason against the order.
- A change in payment or credit status triggers the same check again before release.
Practical checklist
- The systems of record for receivables and payments are explicitly named.
- Credit-limit and overdue rules are approved by the finance owner.
- An exception cannot proceed without an accountable person and a reason.
- The warehouse receives an unambiguous status without reconciling reports by hand.
Scope and limits
Distribution credit control supports an operational decision but does not replace financial accounting or the company’s contractual policy. Financial data sources and legal grounds are defined within the implementation.